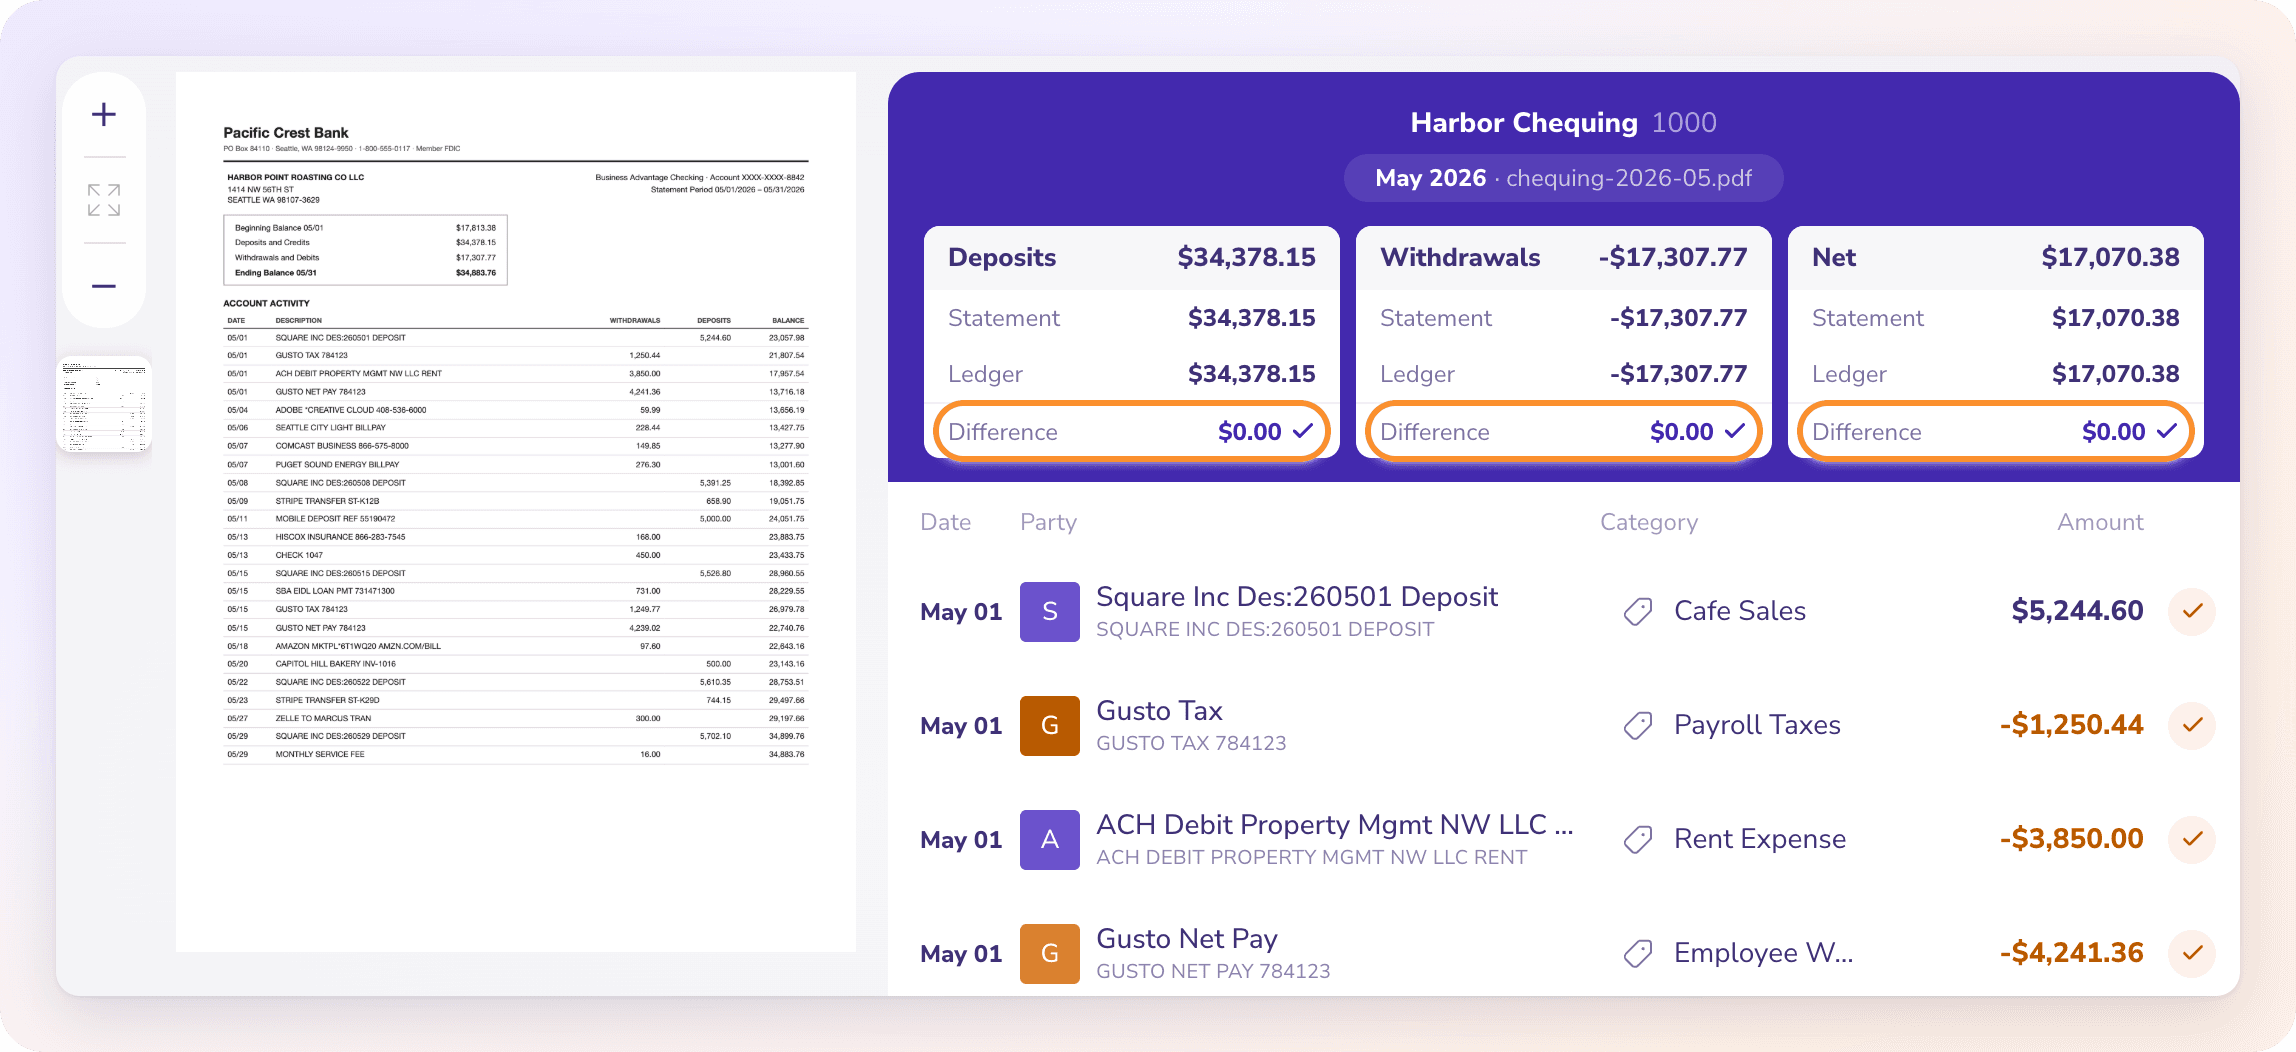
Multi-currency bank reconciliation, tied in the account’s currency, then valued in yours.
Reconcile a foreign-currency bank account in its own currency first: the statement’s opening balance plus its lines must equal its closing balance, exactly as printed. Then value the closing balance at the month-end rate in your home currency and book the change as an exchange gain or loss. ZeraBooks AI bookkeeping follows the same bank reconciliation method.
The change in the home-currency value of foreign money you still hold, or still owe or are owed, because the exchange rate moved. It becomes realized when the money is actually received, paid or converted.
THE METHOD
How do you reconcile a foreign-currency bank account?
In two passes. The bank only knows the foreign currency, so the statement can only prove the account in that currency. The home-currency figure is your books’ measurement of it.
1
Reconcile in the account’s currency
Match every line and agree the closing balance to the statement, to the cent, in Canadian dollars, euros or whatever the account holds. Exchange rates play no part in this pass.
2
Check each line’s home-currency value
Every deposit and payment was recorded at a rate on its own date. Receipts and payments against invoices and bills settle at a different rate from the one the document was booked at; that gap is a realized gain or loss.
3
Value the closing balance at the month-end rate
Multiply the foreign closing balance by the rate on the last day of the month. The difference from the home-currency amount carried in the books is an unrealized gain or loss.
4
Record the adjustment
Post the unrealized amount so the balance sheet shows the account at today’s value. Many accountants reverse it on the first of the next month and measure again at the next month-end.
We set you up and catch up your past months for free. Then ZeraBooks keeps your books done.
What does the reconciliation look like in the foreign currency?
Maple & Tide Trading is a fictional U.S. importer that keeps its books in USD and holds a Canadian-dollar checking account ending 5820. Its June 2026 statement, in CAD:
Date
Line
CAD in
CAD out
CAD balance
06/01
Opening balance
20,000.00
06/10
Payment from Harbourline Foods, invoice of May 20
8,000.00
28,000.00
06/18
Payment to Cedar Ridge Packaging, bill of June 2
5,500.00
22,500.00
06/30
Monthly account fee
25.00
22,475.00
June
Closing balance
8,000.00
5,525.00
22,475.00
20,000.00 + 8,000.00 − 5,500.00 − 25.00 = 22,475.00, the closing balance printed on the statement. If the books’ CAD balance for the account is also 22,475.00, pass one is done. No rate has been used yet.
WORKED EXAMPLE, PASS TWO
How do you calculate realized and unrealized exchange gains?
The same month in USD. Rates are USD per 1 CAD and invented for the example. Each line is recorded at its own date’s rate; the documents behind the two payments were booked earlier, at other rates.
Item
CAD
Rate
USD
Gain or loss
Opening balance carried
20,000.00
0.7300
14,600.00
Invoice of May 20, as booked
8,000.00
0.7280
5,824.00
Received June 10
8,000.00
0.7350
5,880.00
56.00 realized gain
Bill of June 2, as booked
5,500.00
0.7360
4,048.00
Paid June 18
−5,500.00
0.7400
−4,070.00
22.00 realized loss
Fee June 30
−25.00
0.7380
−18.45
Carried at June 30
22,475.00
16,391.55
Valued at June 30 rate
22,475.00
0.7380
16,586.55
195.00 unrealized gain
Carried: 14,600.00 + 5,880.00 − 4,070.00 − 18.45 = 16,391.55. Valued: 22,475.00 × 0.7380 = 16,586.55. The difference, 195.00, is unrealized because Maple & Tide still holds the Canadian dollars. The realized amounts net to 56.00 − 22.00 = 34.00: the customer’s CAD was worth more when it arrived than when invoiced, and the supplier cost more to pay than when billed.
THE ENTRIES
What journal entries does a multi-currency reconciliation need?
Maple & Tide’s June entries in USD. CAD checking is the bank account; the receivable and payable were recorded when the invoice and bill were booked.
Event
Debit
Credit
USD
06/10 customer pays
CAD checking 5,880.00
Accounts receivable 5,824.00
Exchange gain or loss 56.00
5,880.00
06/18 pay supplier
Accounts payable 4,048.00
CAD checking 4,070.00
Exchange gain or loss 22.00
4,070.00
06/30 bank fee
Bank fees 18.45
CAD checking 18.45
18.45
06/30 revalue the balance
CAD checking 195.00
Exchange gain or loss (unrealized) 195.00
195.00
After the last entry CAD checking shows 16,586.55 in USD, which is 22,475.00 CAD at the June 30 rate. Some businesses keep realized and unrealized amounts in separate accounts so the profit and loss shows which is which; your accountant decides. At month end, the revalued 16,586.55 is the figure a balance sheet reconciliation of the account should agree to.
QUICKBOOKS VS XERO VS ZERABOOKS
How QuickBooks Online, Xero and ZeraBooks handle a foreign-currency bank account
QuickBooks Online and Xero from their own help and product pages; ZeraBooks from its Help Center. We make ZeraBooks.
Feature
QuickBooks Online
Xero
ZeraBooks
Which plans
Essentials, Plus, Advanced; not Simple Start
Established plan (US)
Included in the ZeraBooks subscription
Currencies
Add currencies under Settings, Currencies
Over 160
Books in USD, CAD or EUR; accounts in one of the other two
Turning it on
Account and settings, Advanced, Currency; can’t be turned off, home currency then fixed
Foreign bank accounts can be added once multi-currency is on
Pick the account’s currency when adding it; books currency locks at the first transaction
Account currency
One per account; fixed once a transaction posts
One per foreign currency bank account
One per account; locks when the first statement lands
Exchange rates
Update automatically every 4 hours, or enter your own
Hourly rates
Journal lines and documents use the rate for their date
Gains and losses
Revalue Currency: A/R and A/P show as unrealized, bank accounts as realized
Realized on payment; bank revaluation account for foreign bank balances; unrealized for open invoices and bills
Payment differences on bills and invoices go to Exchange Gain or Loss
Watch out for
Can’t revalue while the books are closed
Plan upgrade needed from Early or Growing
No currencies beyond USD, CAD and EUR; no foreign opening balances when moving books
Competitor facts from their public pages, checked October 22, 2026: Intuit: Set up and use Multicurrency in QuickBooks Online · Intuit: Enter home currency adjustments for your foreign balances · Xero: Multi-currency accounting (US) · Xero Central: Foreign currency accounts in the chart of accounts. Prices and features change; check each vendor before you buy.
WHERE IT GOES WRONG
Why doesn’t my foreign-currency account reconcile?
Most problems come from mixing the two passes. Tell which pass is off first.
Off in the foreign currency
A normal reconciliation problem: a missing line, a doubled line, a flipped sign. Rates can’t cause a difference in pass one, so don’t look for one there.
Ties in CAD, odd in USD
A line was recorded at the wrong date’s rate, or an amount was entered in USD into the CAD account. Re-check the rate on each line against its date.
The bank converted for you
A payment from the CAD account to a USD supplier shows the CAD the bank took. Record what left the account in CAD; the bank’s rate decides the USD cost.
Revaluation never reversed
If last month’s unrealized entry stays in and this month’s is measured from the original carried amount, the gain is counted twice. Reverse it, or measure from the revalued figure; don’t mix.
Wrong account for the statement
A CAD statement uploaded or imported into a USD account. Every line is the right number in the wrong currency.
IN ZERABOOKS
Foreign-currency accounts in ZeraBooks.
ZeraBooks keeps each company’s books in one currency, USD, CAD or EUR, and lets a bank or card account be held in one of the other two.
ONE CURRENCY PER ACCOUNT
The statement has to match the account.
When you add a bank or card account, choose its currency if it differs from the books. Statements upload in that currency, and the currency locks once the first statement lands. A statement that names a different currency from its account isn’t imported, which stops the wrong-account mistake above. Each statement is then checked against its own printed opening and closing balance.
A bill or invoice in another of the three currencies posts at the exchange rate on its date, and any difference when it is paid goes to Exchange Gain or Loss, the realized amount in the example. A journal entry line in a foreign account is converted at the entry date’s rate and must balance in the books currency. More in the general ledger guide.
What is the difference between realized and unrealized exchange gains?+
Realized gains and losses come from money that actually changed hands: a customer paid in CAD worth more or less than when you invoiced. Unrealized ones are on money you still hold or are still owed, measured at today’s rate, and can change again before you settle.
Do I reconcile a foreign bank account in my home currency?+
No. Reconcile it in the account’s currency against the statement, because that is the only currency the bank prints. The home-currency value is a measurement you add afterwards at the month-end rate. Foreign business accounts may also come as MT940 files, a bank format more common outside the U.S.
Which exchange rate should I use at month end?+
The closing rate for the last day of the period from the source your books use, applied the same way every month. QuickBooks Online and Xero each fetch rates automatically; your accountant may prefer a specific published rate.
Does QuickBooks Online show bank revaluation as realized or unrealized?+
Intuit’s help on home currency adjustments says adjustments on accounts receivable and payable show as unrealized, and on bank and other accounts as realized. Check with your accountant if your reporting needs the bank amount split out.
Do I need a separate bank account in my books for each currency?+
Yes, in all three products. QuickBooks Online allows one currency per account, Xero sets up a bank account per foreign currency, and ZeraBooks gives each bank or card account one currency that locks when its first statement lands.
Can ZeraBooks keep books in other currencies?+
Only US dollars, Canadian dollars and euros. A company picks one as its books currency, and accounts can be held in the other two. ZeraBooks is $79 a month billed annually or $149 monthly after a 7-day trial; see ZeraBooks pricing.
Damin founded ZeraBooks in 2025 and still talks to the bookkeepers, firms and owners who use it every week. He writes about what he sees in their statements and ledgers, and every page here is checked against the live product before it goes up.
Upload a statement in its own currency. Checked against what the bank printed.
Add the account in USD, CAD or EUR, upload the statement, and watch it tie in its own currency. Free for 7 days, then $79 a month billed annually. Prefer to hand it off? See our bookkeeping services.